SBA 504 loans
Long-term fixed-rate financing for the building you operate from. Ten percent down, a rate locked for the life of the loan, and terms to 25 years.
Three pieces, not one
A 504 isn’t a single loan. It’s a capital stack, and the structure is the entire reason to use one.
| Piece | Share | What it is |
|---|---|---|
| Bank first mortgage | ~50% | A conventional loan at the lender’s own rate and terms, in first lien position |
| CDC debenture | ~40% | SBA-guaranteed, fixed for the full term, second lien |
| Your equity | 10% | The down payment |
The bank carries half at market terms. The CDC portion is where the advantage sits: a fixed rate set at the monthly debenture sale and held for the entire 10, 20 or 25-year term, with no reset and no balloon. On a conventional commercial mortgage you’d typically be looking at 20 to 30 percent down and a rate that resets every five years.
Your share moves with the deal:
- Standard owner-occupied property — 10%
- Startup, or a special-purpose property — 15%
- Both a startup and a special-purpose property — 20%
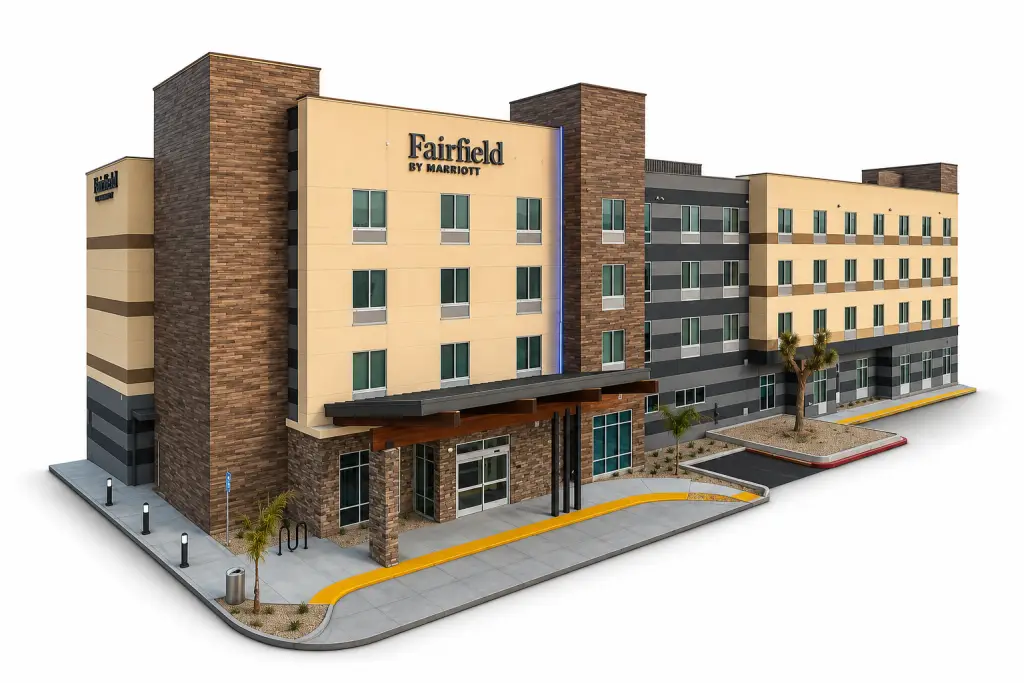
Special-purpose covers hotels, gas stations, car washes and anything else that’s hard to repurpose. The stack shifts to 50-35-15 rather than 50-40-10.
Whether you qualify
- Operating for profit in the United States
- Tangible net worth under $20 million
- Average net income under $6.5 million after federal taxes across the last two years
- Occupancy: at least 51% of an existing building, or 60% of new construction
- Fixed assets only — real estate, or equipment with ten or more years of useful life. Not working capital, not inventory, not rental property.
- One job created or retained per $95,000 of debenture, or the project meets a public policy goal instead
- Every owner of 20% or more files SBA Form 413 and generally signs a personal guarantee
- As of March 1, 2026, all direct and indirect owners must be U.S. citizens or U.S. nationals
How much, and at what rate
The maximum applies to the CDC debenture, not the project. A $5 million debenture supports a project of roughly $12.5 million once the bank’s 50% and your 10% are added.
- $5 million standard debenture maximum
- $5.5 million for small manufacturers and eligible energy projects
Rates are set at a monthly SBA debenture sale, priced at a spread over Treasuries, then fixed for the life of the loan. The 20 and 25-year terms price every month; the 10-year prices in odd-numbered months only. The all-in effective rate adds roughly a point of ongoing program fees to the debenture rate.
On prepayment: the penalty attaches only to the CDC second lien and declines to zero at the halfway point of the term. You can refinance the bank’s first lien without triggering it — a flexibility most borrowers don’t realize they have.
504 refinance and cash-out
A 504 can refinance existing qualifying debt, including conventional commercial mortgages, and in some cases pull cash out against accumulated equity for eligible business expenses. If you’re carrying a commercial mortgage that resets or balloons in the next eighteen months, this is worth pricing now rather than at sixty days out.
FAQ
How much do I put down on a 504?
Ten percent of total project cost on a standard owner-occupied property. Fifteen percent for a startup or a special-purpose property such as a hotel or gas station, and twenty percent when both apply.
What's the maximum?
$5 million on the SBA debenture, or $5.5 million for small manufacturers and eligible energy projects. Because the debenture is roughly 40% of the stack, that supports a total project around $12.5 million.
Can I use a 504 for working capital?
No. The 504 is for fixed assets — real estate and long-life equipment. Working capital needs a 7(a).
Do I have to occupy the building?
Yes. At least 51% of an existing building, or 60% of new construction. Investment property doesn’t qualify.
Is the rate really fixed for the whole term?
There’s no SBA-mandated minimum, but lenders set their own and most look for 680 or better, alongside debt service coverage of roughly 1.15x. The credit score is rarely what kills a deal — cash flow and structure are.
Can I combine a 504 with a 7(a)?
Yes, and since July 4, 2026 more easily than before. A 7(a) balance no longer reduces your 504 debenture maximum, and the combined ceiling is $10 million.
What we've done
Since 0
Financing special-purpose property
$ 0 M+
Funded in SBA transactions
0 +
Loans closed
0 States
Nationwide
Purchases, refinances, cash-out refinances, ground-up construction and bridge. Hotels and motels, flagged and independent. Gas stations with and without c-store. Car washes. Self storage. Daycare, retail, office and light industrial where the owner occupies the building.
Trusted by Business Owners Nationwide
They understood the deal, not just the loan.
We were looking for financing to purchase a gas station and had already spoken with a couple of lenders who couldn’t give us a clear path forward. SBA Finance Group took the time to understand the business, walked us through our options, and helped us structure the financing from beginning to end. Having someone who understood this type of transaction made a huge difference.
They made a complicated process much easier.
Financing a hotel purchase can get complicated quickly. The SBA Finance Group team was responsive, straightforward, and always kept us informed about what was needed next. They helped us work through the financing process and kept the transaction moving toward closing. I would absolutely work with them again.
We finally felt like someone was working with us.
What stood out was the level of communication. Instead of simply telling us whether a deal fit into a lending box, they helped us understand the different options available and what made the most sense for our business. We were able to secure financing for our acquisition and move forward with confidence.